Quick Answer: Novato's appraisal-gap risk is concentrated in ZIP code 94949 and grew through 2026. Per BAREIS MLS, Novato's fast-lane single-family sales closed at 102.28% of original list price in Q2 2026 (April 1 – June 30), up from 100.65% in Q1, and 94949 homes went into contract in a median of 17 days with 46% selling in 14 days or less. Because an appraisal is built from closed comps in prior months, a rising overbid can outrun the comp set. Conventional buyers should write a capped, contingency-backed gap commitment. VA buyers keep the amendatory clause, which cannot be waived, and prepare for the Tidewater window before the appraiser ever visits.
Key Takeaways — per BAREIS MLS, single-family homes:
- Novato's fast-lane sales closed at 102.28% of original list in Q2 2026, up from 100.65% in Q1 — the overbid is growing, and so is the appraisal exposure that comes with it.
- 94949 is Novato's appraisal-gap ZIP: 37 Q2 closings, a 17-day median days on market, and 17 of 37 sales (46%) closed in 14 days or less.
- Marin's Q2 2026 Sprint-vs-Stale spread ran from 105.72% of original list (in contract within 30 days) to 84.24% (120+ days) — roughly $385,000 on a median-priced home — and an appraiser's comp set can contain both.
- The VA amendatory clause cannot be waived by a seller's request; VA buyers compete with a capped, written gap commitment instead.
- Tidewater gives a VA lender two business days to submit stronger comps before the Notice of Value is final.
- A gap-coverage figure chosen before the offer goes in converts an open-ended surprise into a number you decided on your own terms.
The call from your agent says you got it. Offer accepted, seller signed, champagne feels appropriate. Then, three to four weeks later, a second call arrives with a dollar figure attached: the appraisal came in under contract price, and someone has to cover the difference before the lender will fund.
That second call has become more common in Novato as 2026 has gone on, and it is not evenly distributed across the city. If you are buying in the fast lane of 94949, your odds of getting it are meaningfully higher than they were in January. If you are financing with a VA loan, the fix looks different than it does for a conventional buyer. I live in Pointe Marin, I pull the BAREIS MLS numbers for Novato every quarter, and I spent years as a litigation attorney before I sold my first Marin home. Here is what the data says, and how I structure offers around it.
Why did Novato's appraisal-gap risk grow through 2026?
Novato's fast-lane overbid rose from 100.65% of original list price in Q1 2026 to 102.28% in Q2, per BAREIS MLS, while 94949 accelerated from a 19-day median days on market to 17. Contract prices pulled further ahead of the closed comps an appraiser is required to use, and that distance is the appraisal gap.
In Q1 2026 (January 1 – March 31), Novato recorded 70 closed single-family sales at a 22-day median days on market. Roughly seven in ten went into contract within 30 days, and that fast cohort averaged 100.65% of original asking price — barely over ask. Inside 94949, 20 homes closed at a 19-day median, and every one of Pointe Marin's four Q1 sales was in contract within 30 days.
By Q2 2026 (April 1 – June 30), the fast cohort had shrunk to 64% of Novato's closings, but it was paying more: 102.28% of original list. That combination — fewer fast sales, each clearing further over ask — is exactly the profile that produces low appraisals. The market is sorting harder, and the winners of those contests are paying a premium the trailing comps have not caught up to. 94949 posted the sharpest move in the city: 37 closings, up 15.6% year over year, a 17-day median days on market (down from 22 a year earlier), an average that fell from 32 days to 24 over the same year, and 17 of 37 sales (46%) closed in 14 days or less.
An appraisal is backward-looking by design. It leans on closed comparable sales from the weeks and months before your offer, not on where the market is trending the day you sign. A buyer who escalates $40,000 above list in September is being valued against a summer comp set that includes calmer, more evenly split closings from earlier in the year. The gap between what a competitive market will pay and what a recent-comps appraisal will support tends to widen as momentum builds, and Novato's 2026 numbers show that widening in progress.
Which Novato ZIP code carries the most appraisal-gap risk?
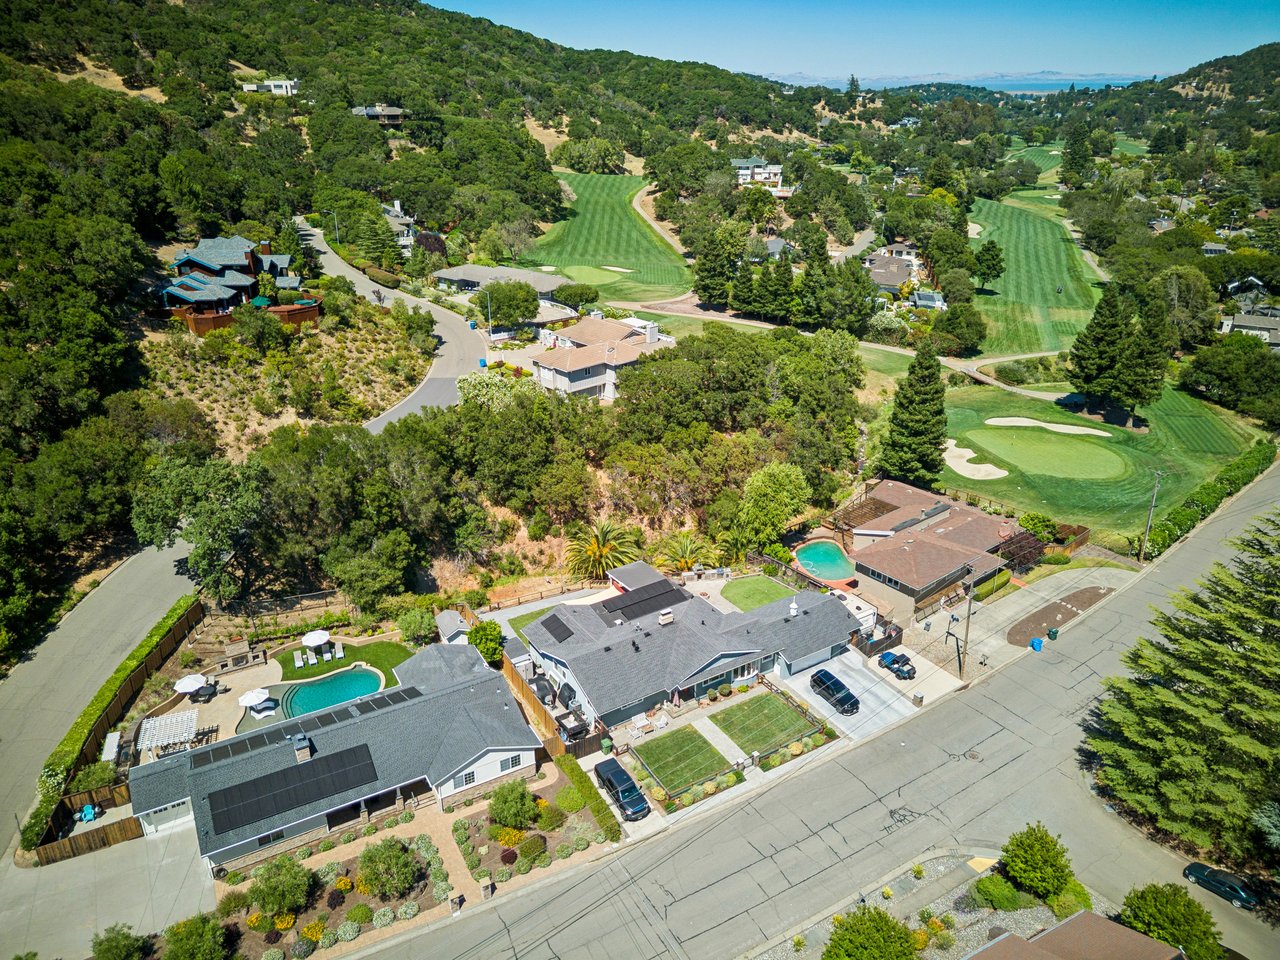
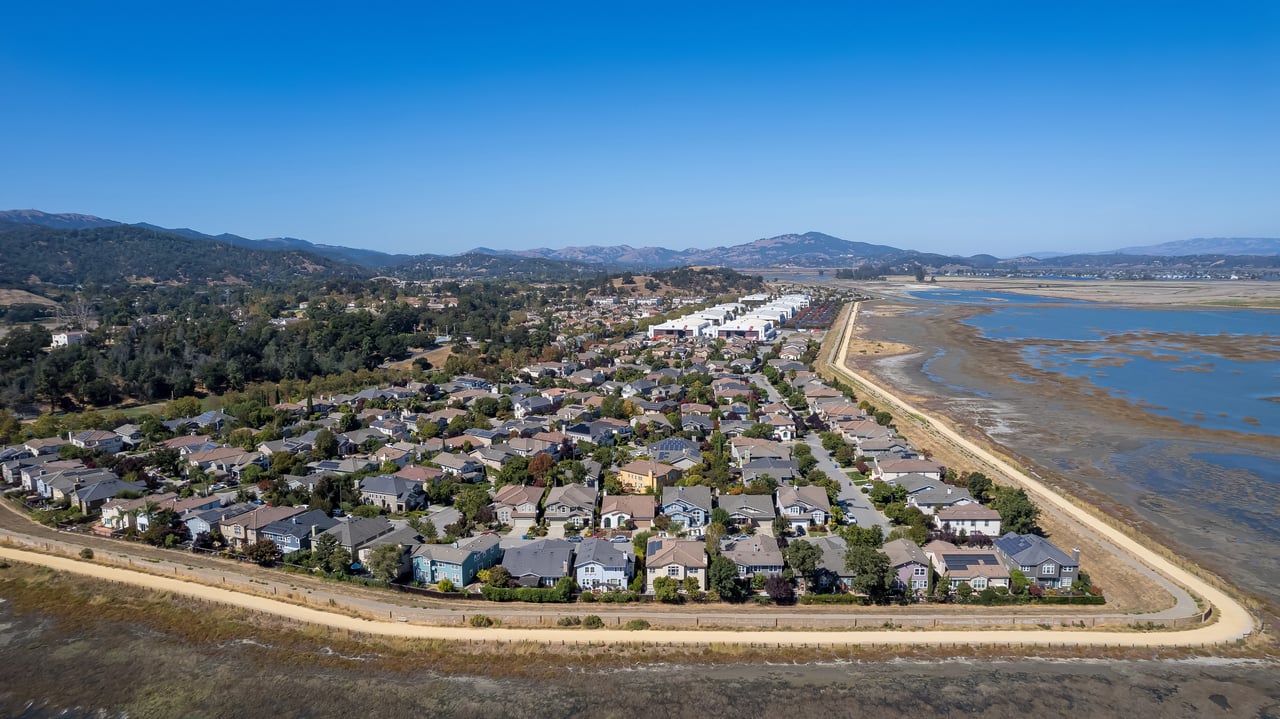
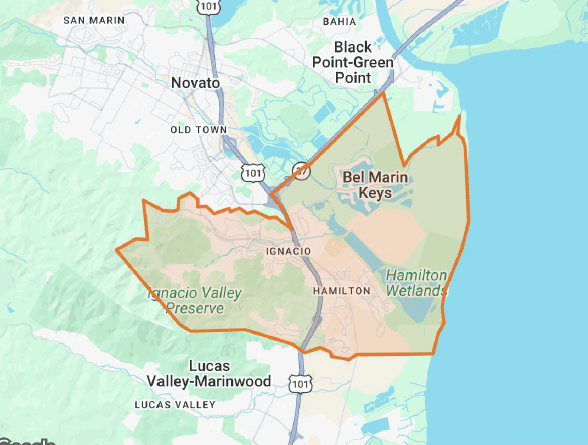
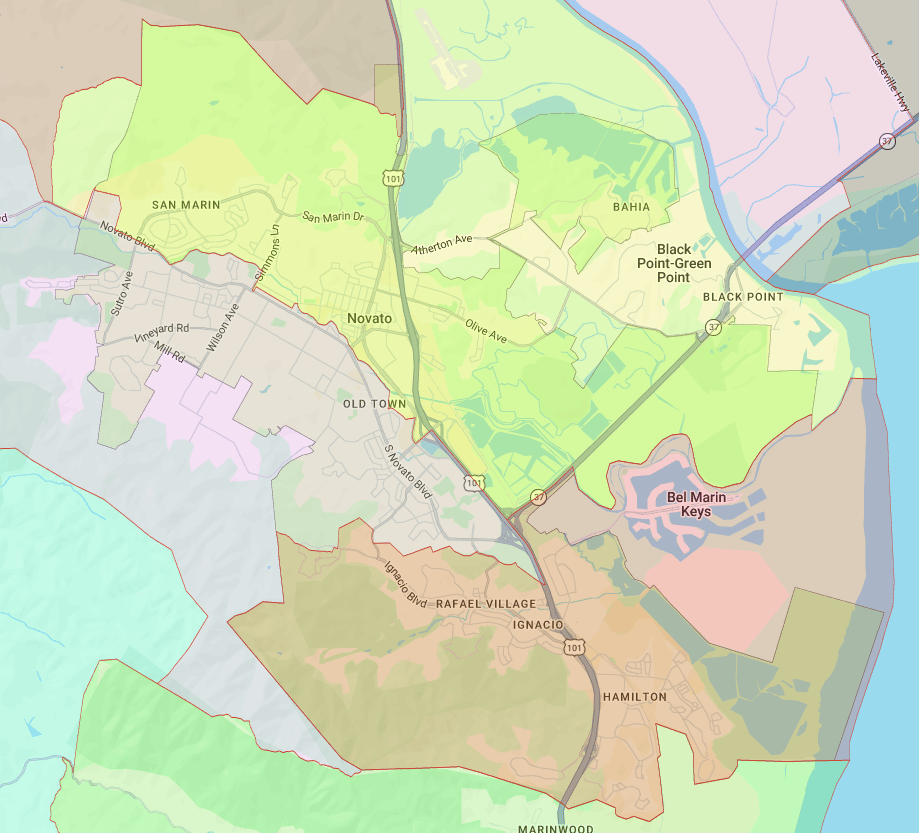
94949 — South Novato's Pointe Marin, Hamilton Field, Bel Marin Keys, Loma Verde and Marin Country Club Estates — carries the most appraisal-gap exposure in Novato, because it is the fastest and most competitive of the city's three ZIP codes. Novato is really three markets stitched into one city, and the friction concentrates in one of them.
ZIP code | Sub-markets | Q2 2026 closed sales | Median sale price | Median $/sq ft | Speed signal |
|---|---|---|---|---|---|
94949 (South Novato) | Pointe Marin, Hamilton Field, Bel Marin Keys, Loma Verde, Marin Country Club Estates | 37 (+15.6% YoY) | $1,525,000 | $670 | Median 17 days on market (down from 22); 46% of sales closed in 14 days or less — highest appraisal-gap exposure |
94945 (North Novato) | Old Town, San Marin, Cheda Knolls | 49 (+40.0% YoY) | $1,131,970 | $618 | Median 23 days on market (flat); entry-level volume surge — moderate exposure |
94947 (Central & West Novato) | Indian Valley, Pleasant Valley, the west side | 49 (−9.3% YoY) | $1,250,000 | $626 | Most current listings in Novato on July 1 (39), only 28% in escrow — the most room for an appraisal to agree with you |
Source: BAREIS MLS, closed single-family detached sales including Sold Off MLS, April 1 – June 30, 2026. Condos and townhomes excluded. Full ZIP breakdown in my Novato Q2 2026 market report.
The spring 2026 window (March 1 – June 1) told the same story from a different angle: 94949 averaged 24 days on market, the fastest in Novato, and 94947 averaged 37, the slowest. A home that goes into contract in under two weeks almost by definition drew competing offers before an appraiser ever set foot inside. A home that takes five or six weeks has usually found its price through ordinary negotiation, which leaves less daylight between contract price and appraised value.
One more 94949 wrinkle: 5 of the ZIP's 37 Q2 closings were recorded as Sold Off MLS, the highest off-market share in the city. Those comps exist in BAREIS, but an appraiser will often give them less weight because the home never had open-market exposure, and some automated comp tools skip them entirely. In a 37-sale quarter, losing five comps changes the answer. It is one more reason the comp packet for a 94949 offer gets built by hand — more on how Marin's off-market sales work here.
Why can't the appraiser just split the difference?
Because Marin's closed comps are split into two markets. Per BAREIS MLS, the 76% of Marin single-family homes that went into contract within 30 days in Q2 2026 closed at 105.72% of original list price, while homes that sat 120+ days closed at 84.24% — roughly $385,000 apart on a median-priced home. An appraiser working a Novato file can be looking at both stories in the same neighborhood and the same quarter.
I call this Sprint vs. Stale, and it is the framework behind every offer I write. Novato sits at the disciplined end of the spectrum: a 64% Sprint share at 102.28% of original list, plus the county's deepest 31-to-60-day tier, 31 sales at 95.36% of original list. Read together, that says Novato's fast sales are not emotional bidding wars. They are modest, rational overbids. But it also means an appraiser can legitimately pull one comp that closed at 102% of list and another that closed at 95% from the same street, and which ones land in the report decides your gap. The appraisal risk in 94949 is not about buyers losing their heads. It is about a market where even a small, defensible overbid can outrun a comp set that has not caught up yet.
County-wide context lives on my Marin Market Intelligence page, which I refresh every quarter with the BAREIS pull behind these numbers.
What is the VA amendatory clause, and why can't a seller ask you to waive it?
The VA amendatory clause — often called the escape clause — is a federally required term in every VA-financed purchase contract. It lets the buyer cancel and recover the earnest money deposit if the home's VA-appraised value comes in below the purchase price, and a seller cannot require a VA buyer to waive it, because it is not the buyer's clause to give up. It is a protection built into the loan program itself.
This matters more in Novato than in most of Marin. Hamilton Field is a former Air Force base, a VA loan requires no down payment for eligible borrowers with full entitlement, and Novato is Marin's most affordable city — so VA financing is a live part of the offer conversation here in a way it is not in Tiburon or Ross.
What the clause actually does. If the VA's Notice of Value comes in under the contract price, the buyer is not obligated to complete the purchase and does not forfeit the earnest money deposit. The buyer keeps the option to proceed anyway and cover the difference in cash. In California the clause typically rides along on the C.A.R. FHA/VA Amendatory Clause form. What the clause does not do is stop a VA buyer from competing: it changes the tool.
That single fact changes the strategy for a VA buyer in Novato's fast lane. Waiving the appraisal contingency to look stronger, the standard multiple-offer play, is not available. What is available is a defined gap-coverage commitment: a written agreement to cover a specific dollar amount above the appraised value in cash, backed by proof of funds, while the amendatory clause still protects the buyer if the shortfall runs deeper than that number.
VA loans also carry a built-in second chance called Tidewater. Under VA Circular 26-17-18, if the appraiser expects the value to come in below contract price, the appraiser notifies the lender's point of contact before finalizing the report, and the lender has two business days to submit additional comparable sales. No value is disclosed at that stage, only that it is short. If the final Notice of Value is still low, the buyer or seller can request a formal Reconsideration of Value through the lender under the VA Lender's Handbook, based on factual errors in the report or superior closed comps the appraiser did not use. In a market where Sprint and Stale sales sit side by side, the comps you hand the appraiser inside that two-business-day window are the whole ballgame.
A note from a former litigation attorney: this is market analysis, not legal advice. The clause language, your lender's guidelines and the VA's current rules govern your transaction, and your VA lender should walk you through them before you write.
How do you structure a Novato offer that survives its own appraisal?
You decide the gap number before the offer goes in, not after the appraisal comes back low. The tactical fixes are not exotic, but every one of them has to be in place on the day you write.
- Get fully underwritten, not just pre-approved. I advise every buyer to obtain full underwriting up front so the offer reads like cash. It also means your lender can tell you, before you escalate, exactly how much cash a $25,000 or $50,000 gap would require on your loan.
- Set a specific gap-coverage dollar figure in writing. In California, the C.A.R. Residential Purchase Agreement lets you keep the appraisal contingency but set it to trigger only if the appraisal comes in more than a stated dollar amount below the purchase price. C.A.R. itself calls that the right way to write gap coverage; the vague "buyer will pay $X above the appraised value" language is the wrong way, because it can be read three different ways when the report lands.
- Keep the contingency alongside the cap. The two are not mutually exclusive. Pairing them tells the seller you are serious while keeping your total cash exposure known in advance, and it leaves you a safety net if the shortfall runs past the number you committed to.
- Pull the actual comps before you escalate, not after. I run the last 90 days of the sub-market through the Sprint-vs-Stale lens, including the Sold Off MLS entries, before we pick a number. If the neighborhood's recent closings skew Sprint, we can defend a higher price. If they skew Stale, you are escalating into thin air.
- If you are financing with a VA loan, have the Tidewater comp packet ready on day one. The two-business-day window only helps if the comps already exist and someone is watching for the notice. Know the Reconsideration of Value path before you need it.
- Reserve the gap cash separately. Set it aside before you are in contract, apart from down payment, closing costs and reserves — not after the appraisal report lands on a Friday afternoon with a Monday deadline attached.
None of this eliminates the risk. It converts an open-ended surprise into a number you chose in advance, which is the entire point.
If you are the seller reading this: a capped gap commitment backed by proof of funds from a fully underwritten buyer is often worth more than a blanket appraisal waiver from a buyer who may not be able to fund it. When I advise sellers on multiple offers, I underwrite the buyer, not just the price.
What happens after your Novato offer is accepted?
The signature is where the testing starts, not where it ends. I spent years as a litigation attorney before I sold my first Marin home, and I still read a purchase contract the way I read a pleading: an accepted offer in 94949 is a promise with a contingency still hanging off it, and the appraisal is where that promise gets checked against the market's own math. Between acceptance and funding, your job is to make sure the appraiser sees the same market you saw when you wrote the number.
If you are weighing an offer in Pointe Marin, Hamilton Field, Bel Marin Keys, Loma Verde or Marin Country Club Estates, or you are a VA-eligible buyer trying to work out how the amendatory clause plays out in this specific market, I will walk through your exact numbers before you write the offer, not after the appraisal report shows up. The Marin Buyer's Guide covers the rest of the process, and the Imagine Marin video library has the quarterly data walk-throughs behind this article.
Build the gap-coverage math around the home you actually want, not a generic playbook.
Kyle Frazier, JD, CRS, CLHMS · Broker Associate, Compass · DRE# 01405738
[email protected] · 415-350-9440
Frequently Asked Questions
What is an appraisal gap?
An appraisal gap is the difference between the price a buyer agreed to pay and the value a lender's appraiser assigns to the home. Lenders base the loan on the lower of the two, so if the appraisal comes in under the contract price, the buyer has to cover the shortfall in cash, renegotiate the price, challenge the value, or cancel under an appraisal contingency if one is in place.
How do I know if a Novato home is likely to appraise below the contract price?
BAREIS MLS does not record appraisal results, but it records the conditions that produce low appraisals: speed and overbid. In Q2 2026, 94949 homes went into contract in a median of 17 days, 46% sold in 14 days or less, and Novato's fast-lane sales closed at 102.28% of original list. Before you escalate, pull the last 90 days of sub-market comps, including Sold Off MLS entries, and see whether your number is supported by closed sales rather than by the competition.
Can a seller ask a VA buyer to waive the appraisal contingency?
No. Every VA-financed purchase contract carries the VA amendatory clause, which lets the buyer cancel and recover the earnest money deposit if the VA-appraised value comes in below the purchase price. It is a federal program requirement, not a negotiable buyer contingency, so a seller cannot make waiving it a condition of acceptance. A VA buyer competes instead with a written, capped gap-coverage commitment backed by proof of funds.
What is the VA Tidewater process?
Tidewater is the VA's early-warning step, set out in VA Circular 26-17-18. When a VA appraiser expects the value to come in below the contract price, the appraiser notifies the lender's point of contact before finalizing the report, and the lender has two business days to submit additional comparable sales and market data. The appraiser then issues the final value. If it is still low, the parties can request a formal Reconsideration of Value through the lender.
How much appraisal-gap coverage should I offer in 94949?
There is no universal number, and the wrong way to pick one is to match the competition. The right way is to price the strongest value the closed comps will defend, measure the distance between that figure and your offer, and cap your coverage at cash you can actually fund beyond down payment, closing costs and reserves. In Q2 2026 Novato's fast-lane sales closed at 102.28% of original list per BAREIS MLS, so defensible gaps here are a few percent of price, not blank checks.
Does a seller ever prefer an appraisal contingency to a full waiver?
Sometimes, yes. A buyer who waives every protection can look strong on paper but may walk from the deal anyway if the numbers do not work and the cash is not there to cover the gap. A clearly capped gap-coverage commitment, backed by proof of funds and a fully underwritten loan, often reads as more credible to a seller than a blanket waiver from a buyer the seller suspects cannot actually honor it.
Does paying cash make the appraisal irrelevant?
It removes the lender from the equation, which removes the forced connection between appraised value and loan amount. It does not change what the home is worth. A cash buyer who overpays relative to the closed comps takes on the same long-term equity risk, just without a lender flagging it first. Cash buyers can still order an appraisal as due diligence, with a contingency written to match their timeline.
Is 94947 the safer Novato ZIP code if I want to avoid appraisal risk?
It carries less of this specific friction. On July 1, 2026, 94947 had the most current listings in Novato, 39, with only 28% in escrow, so buyers there face fewer competing offers and appraisals have more room to agree with the contract price. But buyers choose 94949 for reasons unrelated to appraisal risk — newer construction in Hamilton Field and Pointe Marin, lagoon access in Bel Marin Keys, Marin Country Club Estates' golf-course setting. If that is the fit, plan for the gap instead of avoiding the ZIP code.
What happens if a conventional appraisal comes in low in Novato?
You have four paths: ask the seller to reduce the price to the appraised value or meet somewhere between, cover the difference in cash, ask your lender to submit a reconsideration of value with stronger closed comps or corrections to factual errors in the report, or cancel and recover your deposit if your appraisal contingency is still in place. Which path is realistic depends on decisions you made when you wrote the offer, which is why the gap number gets set first.
Data: BAREIS MLS, closed single-family sales including Sold Off MLS; condos and townhomes excluded. Q1 2026 = January 1 – March 31; spring window = March 1 – June 1; Q2 2026 = April 1 – June 30. Analysis: Imagine Marin. VA program references: VA Lender's Handbook (Pamphlet 26-7) and VA Circular 26-17-18. This article is market analysis by a former litigation attorney and licensed California real estate broker; it is not legal advice.